Why Earning More Money Doesn’t Always Mean You’re Getting Ahead
Have you ever received a raise, landed a better-paying job, or started making more money from your business, only to look at your bank account a few months later and wonder where it all went? You expected to feel more comfortable, maybe save a little more, pay off some debt, or finally stop worrying about every unexpected expense. Instead, your bills seem to have grown right alongside your income, and somehow you’re still waiting for that feeling of financial progress.
You’re not alone. Earning more money can improve your life, but it doesn’t automatically mean you’re building wealth or becoming financially secure. Sometimes, the extra money gets swallowed up by higher expenses, old debts, family responsibilities, or the little upgrades you allow yourself because you feel you’ve finally earned them. Before you know it, you’re making more than you did two years ago, but your financial situation looks almost exactly the same.
Imagine you were earning $50,000 a year and struggling to make everything work. Then you get a new job paying $70,000. Naturally, you’re excited because that extra income should make life easier. You start thinking about moving into a nicer apartment, replacing your old car, eating out more often, or taking the vacation you’ve been putting off.
None of those things is automatically a bad decision. You’ve worked hard, and it’s reasonable to want to enjoy some of the money you earn. The problem starts when every increase in income comes with a matching increase in spending. Your rent goes up because you move somewhere more expensive, your car payment takes a bigger bite out of your paycheck, and weekend brunch becomes a regular expense instead of an occasional treat.
There’s also a less obvious issue: a higher salary doesn’t mean that the full increase lands in your bank account. Taxes, benefit deductions, and retirement contributions can all affect your take-home pay. So while your annual salary may look significantly better on paper, the amount available for everyday spending might be much less impressive than you expected.
This is one reason people can earn more every year without feeling much better off. Their lifestyle keeps expanding to absorb the additional income, leaving little room to build savings or reduce debt. The paycheck gets bigger, but the financial breathing room never really arrives.
One of the easiest ways to confuse earning power with financial progress is to focus on what you can buy instead of what you own or owe. You may be able to afford a newer car, a bigger apartment, expensive clothes, and regular trips without actually having much money set aside for emergencies or the future.
Think about someone who earns a comfortable salary and drives a luxury vehicle, but has a large car payment, thousands of dollars in credit card debt, and barely enough savings to cover one unexpected bill. From the outside, that person might look financially successful. But if the car breaks down, their job disappears, or a medical expense arrives, they could find themselves scrambling to cover the cost.
Now think about someone else who earns less but has a manageable mortgage or rent payment, no high-interest credit card debt, a healthy emergency fund, and money invested for retirement. They might not have the flashiest lifestyle, but they may have more financial security and more freedom to make decisions without panic.
This is why appearances can be misleading. A nice car tells you what someone is driving, not how much debt they have. A beautiful home doesn’t tell you whether the owner can comfortably afford it. And a holiday photo doesn’t tell you whether the trip was paid for with savings or a credit card that will take a year to clear.
Getting ahead financially isn’t about looking rich. It’s about gradually building a life that you can afford today while preparing for the expenses and opportunities that may come tomorrow.
Sometimes the problem isn’t one big purchase. It’s the collection of smaller expenses that become so familiar you stop noticing them.
Maybe you buy lunch at work most days because you’re busy, order delivery when you’re tired, pay for several streaming services, and grab a coffee whenever you leave the house. Each purchase feels manageable on its own, so you don’t think much about it. But when those habits become part of your routine, they can take up a surprising amount of your monthly income.
Let’s say you spend $15 on lunch four days a week. That’s about $240 over a four-week month, before adding drinks, snacks, or delivery fees. You don’t necessarily need to stop buying lunch altogether, but knowing what the habit costs gives you a chance to decide whether it’s worth that amount to you.
The same goes for subscriptions you barely use, gym memberships you haven’t visited in months, and automatic payments you forgot you signed up for. These expenses aren’t always the reason someone struggles financially, and cutting every little pleasure out of life isn’t the answer. The point is to notice where your money is going so that your spending reflects what you actually value.
You may discover that you don’t mind spending money on dinner with friends because those evenings matter to you, but you would happily cancel three subscriptions you rarely open. That’s a much better starting point than feeling guilty about every purchase or trying to follow an unrealistic budget that makes you miserable.
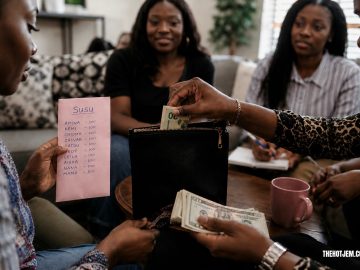
For many Africans in the diaspora, financial decisions involve more than personal bills and savings goals. You may be supporting parents, helping a sibling with school fees, contributing to a family emergency, or sending money home every month. These responsibilities can be meaningful, and for many people, helping family is simply part of how they understand love and responsibility.
But those expenses can also make it harder to get ahead, especially when the requests are unpredictable or you feel guilty saying no. You might receive a raise and decide that you can finally start saving, only for a relative to need help with medical expenses or another family member to ask for money toward a major life event. Before long, the extra income has been committed to several things you hadn’t planned for.
There is no universal answer to how much you should send home or what you should contribute to family needs. Every household has different circumstances, and sometimes relatives genuinely need urgent help. Still, it is worth being honest about what you can afford without putting your own rent, debt payments, emergency savings, or long-term plans at risk.
If you regularly help family, consider building that support into your budget instead of treating it as an unexpected expense every time. You might set aside a specific amount each month and explain when you cannot comfortably contribute more. That doesn’t mean you care less about your family. It means you are trying to make your support sustainable rather than repeatedly putting yourself under financial pressure.
Another reason earning more doesn’t always translate into financial progress is that debt can claim a large portion of your income before you have a chance to use it for anything else. Credit cards, personal loans, car payments, and other obligations can leave you with less money available than your salary suggests.
Imagine getting a raise of $500 a month after taxes, only to discover that your minimum credit card payments, car insurance, and other expenses have increased by roughly the same amount. You might feel as though the raise made no difference because you never actually get to use that money to improve your financial position.
High-interest debt can be particularly frustrating because part of each payment goes toward interest rather than reducing the amount you owe. If you keep adding new purchases to a credit card while trying to pay down the balance, it can feel like you’re working hard without making much progress.
The solution will depend on your situation, but it starts with knowing what you owe, the interest rates you’re paying, and how much of your monthly income is already committed. Paying down expensive debt can free up money over time, giving future raises a better chance of improving your financial position instead of disappearing into old obligations.
Financial progress doesn’t always show up as a designer bag, a new car, or a bigger house. Sometimes it looks like having enough savings to replace a broken refrigerator without using a credit card. It can mean paying your bills on time, bringing down a debt balance, increasing your retirement contributions, or finally having money left over at the end of the month.
It might also mean being able to leave a stressful job without immediately panicking about how you’ll pay your bills, taking a course that could improve your career, or helping a family member without sacrificing your own financial stability. Those things may not be visible to anyone scrolling through your social media, but they can make a meaningful difference in your everyday life.
A useful first step is to look at your last two or three months of spending and compare your income with what actually leaves your account. Check your debts, savings, and retirement contributions too. You don’t need a complicated spreadsheet to begin; even a clear picture of your regular expenses can show you where your money is going and which changes might make the biggest difference.
When your income increases, decide in advance what portion of the extra take-home pay will go toward your goals. You could direct some toward high-interest debt, build your emergency fund, increase retirement contributions, or save for a home deposit. You can still enjoy some of the increase, but giving it a purpose before it disappears makes it easier to see real progress.
It also helps to measure progress against your own starting point rather than someone else’s lifestyle. Your colleague may earn more, your friend may own a home, and someone you follow online may appear to be living a dream life. But their income, debts, responsibilities, and financial support systems may be completely different from yours.
Earning more money is certainly worth celebrating, and increasing your income can open doors that were previously out of reach. But if every extra dollar is already spoken for, a higher salary alone may not change how secure you feel. The goal is not simply to make more money. It’s to use what you earn in a way that gives you more choices, less financial stress, and a better chance of building the future you want.
Discover more from The HotJem
Subscribe to get the latest posts sent to your email.